Valuing semi-annual cash flows, Financial Management

Assignment Help:

In all previous illustrations, we assumed that coupon payments are paid on annual basis. However, most of the bonds carry interest payment semi-annually. Semi-annual coupon payments can be calculated by dividing the annual coupon payment and discount rate by 2. The time period n in the present value formula is treated in terms of 6-month period rather than years.

For example consider a 7%, 5-year bond with a discount rate of 6% and a maturity value of Rs.100. The cash flow, in the form of interest, for the first four and half years will be Rs.3.50 (Rs. 7/2) and last cash flow will be Rs.103.50, i.e., interest of Rs.3.50 and a principal of Rs.100.

The annual discount rate is 6% so semi-annual discount rate will be 3% (6% / 2). 

When coupon rate is 7%, the semi-annual coupon rate is 3.5%. Then PV of cash flow will be:

Table 1: Calculation of PV of 7% Bond when Cash Flows are Semi-annual

Year

Cash Flow (in Rs.)

PV (in Rs.)

  I half 2007

    3.5

  3.40

II half 2007

    3.5

  3.30

  I half 2008

    3.5

  3.20

II half 2008

    3.5

  3.11

  I half 2009

    3.5

  3.02

II half 2009

    3.5

  2.93

  I half 2010

    3.5

  2.85

II half 2010

    3.5

  2.76

  I half 2011

    3.5

  2.68

II half 2011

103.5

77.01


Present Value =

104.27

If we compare the PV of table 1 then we find that PV of table 1 is greater by Rs.0.06. This is because one-half the annual coupon payment is received six months sooner than when payments are annual. 

We can divide the value of non-amortizing bond into two parts, first is PV of coupon payment and second is PV of maturity value. For fixed coupon rate, coupon payments represent an annuity. A short-cut formula for computing the value of bond when coupon rate is fixed and single discount rate is set for discounting the coupon payments, is to compute the PV of the annuity and then add the PV of maturity value.  We can represent it in formula as follows:


         V0      =       335_valuing semi annual cash flows.png
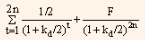
 

                   =       I ¤ 2 (PVIFAkd ¤ 2,2n) + F(PVIFkd/2, 2n)                                           ... Eq. (3)

Where,     

                   V        =    value of the bond

                   I/2      =    semi-annual interest payment

                   F         =    par value of the bond payable at maturity

                    kd/2    =     required rate of return for the half-year period

                   2n        =     maturity period expressed in half-yearly periods.


Related Discussions:- Valuing semi-annual cash flows

Compare the ifrs and gaap revenue recognition policies, SUPERVALU INC . ...

SUPERVALU INC . , a large US retail grocer, had $36.1 billion in sales for its fiscal year ended February 25, 2011. SUPERVALU currently reports using US GAAP. The controller of

Analysis of collaterals, If normal operating revenues are inadequate ...

If normal operating revenues are inadequate to repay the debt, liquidation of collateral may be necessary. Corporate bonds can be either secured or unsecured by c

What do disclaimer of opinion, Disclaimer of Opinion - Statement by an AUDI...

Disclaimer of Opinion - Statement by an AUDITOR indicating inability to express an opinion on the fairness of FINANCIAL STATEMENTS provided and reason for the inability. The audito

Risk of the complete portfolio, (a) Presume we have a portfolio of n name...

(a) Presume we have a portfolio of n names with some default correlation ρ . The risk of the complete portfolio moves according to the change in default correlation. Alternative

How cash budget and capital budget relate to pro forma, Explain how the cas...

Explain how the cash budget and the capital budget relate to pro forma financial statements. The cash budget depicts the projected flow of cash in and out of the firm for fixed

Legal obligations of corporation is the cost of equity zero, If dividends p...

If dividends paid to common stockholders are not legal obligations of a corporation, is the cost of equity zero? Explain your answer. Even though common stockholders don't have

Annuties (ordinary vs due), The values shown in ordinary annuity tables (ei...

The values shown in ordinary annuity tables (either present value or compound value) can be adjusted to the annuity due form by ____ the ordinary annuity interest factor by ____. (

What is the rationale of the double-play strategy, Q. What is the rationale...

Q. What is the rationale of the double-play strategy? The hedge funds deploy a double-play strategy in order to engineer steep increases in interest rates and steep declines in

Profit maximisation decision criterion, Profit Maximisation Decision Criter...

Profit Maximisation Decision Criterion According to this approach, actions which increase profits must be undertaken and those that decrease profits are to be avoided. In speci

Write Your Message!

Captcha
Free Assignment Quote

Assured A++ Grade

Get guaranteed satisfaction & time on delivery in every assignment order you paid with us! We ensure premium quality solution document along with free turntin report!

All rights reserved! Copyrights ©2019-2020 ExpertsMind IT Educational Pvt Ltd