Risk assessment - portfolio management, Risk Management

Assignment Help:

1. You are given the following long-run annual rates of return for alternative investment instruments:

  • US Government T-Bills 3.5%
  • Large-cap common stocks 12.1%
  • Long-term corporate bonds 6.2%
  • Long-term government bonds 5.6%
  • Small-capitalization common stock 14.6%

The annual rate of inflation during the period was 2.9%.  Compute the real rate of return on these investment alternatives.

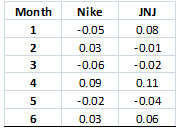
2. The following are the monthly rates of return for TECO Electric and Gold Hill
1393_Risk Assessment - Portfolio Management.png

            Using an excel spreadsheet, compute the following:

a.       Average monthly rate of return for each stock

b.      Standard deviation of returns for each stock

c.       Covariance between the rates of return

d.      The correlation coefficient between the rates of return

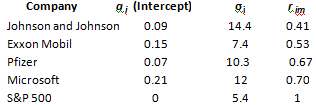
3. Based on five years of monthly data, you derive the following information for the companies listed:
995_Risk Assessment - Portfolio Management1.png

a.   Compute the beta coefficient for each stock

b.  Assuming a risk free rate of 5 percent and an expected return for the market portfolio of 12 percent, compute the expected (required) return for all the stocks.

c.   Plot the following estimated returns for the next year on the SML and indicate which stocks are undervalued or overvalued.

  • Johnson and Johnson-15%
  • Exxon Mobil-10%
  • Pfizer-13%
  • Microsoft-20%

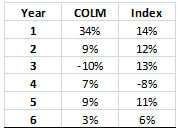
4.  The following are the historic returns for the Columbia Sportswear Company (COLM) and the General Index:
1207_Risk Assessment - Portfolio Management2.png

Based on this information, and using an excel software, compute the following:

a.  The correlation coefficient between COLM and the General Index.

b.  The standard deviation for the company and the Index

c.  The beta for the COLM.


Related Discussions:- Risk assessment - portfolio management

Historical simulation approach, 1) What difference does it make to the Var ...

1) What difference does it make to the Var calculated in Example if the exponentially weighted moving average model is used to assign weights to scenarios as described in Section 1

Risk premium, Risk Premium A risk premium is the extra or excess which ...

Risk Premium A risk premium is the extra or excess which is return on a risky asset relative to the return on risk-free assets. Therefore, it defines the additional return that

Stages of risk management of a project, Problem: (a) What are the two p...

Problem: (a) What are the two primary stages of Risk Management of a project? (b) What are the formalities to consider in a Project Termination Phase? (c) Briefly explain

What is risk appetite?, QUESTION 1 A. Answer all of the following (a...

QUESTION 1 A. Answer all of the following (a) What is risk appetite? (b) List any two risk responses (c) What does ITIL stand for? (d) What is a business case? (

Describe the difference between risk and uncertainty, Problem: (a) Desc...

Problem: (a) Describe the difference between risk and uncertainty. Give an example to illustrate your answer. (b) Name three common measures of risks and outline their p

Currency hedging for exporting and importing company, I want an assignment ...

I want an assignment on a exporting and importing company and how does it do currency hedging and reduce the risk of currency fluctuation

Risk, Explain how budget planning is related risk management

Explain how budget planning is related risk management

Disaster risk management plan, The sustainability of coastal tourism destin...

The sustainability of coastal tourism destinations depends partly on their ability to adapt planning and management practices to the impacts of climate change and also to increase

Challenges, challenges for risk management

challenges for risk management

Write Your Message!

Captcha
Free Assignment Quote

Assured A++ Grade

Get guaranteed satisfaction & time on delivery in every assignment order you paid with us! We ensure premium quality solution document along with free turntin report!

All rights reserved! Copyrights ©2019-2020 ExpertsMind IT Educational Pvt Ltd