Duration, Financial Management

Assignment Help:

Now that we have an understanding about price volatility characteristics of a bond, let us turn to the duration/convexity approach, which is an alternative approach to full valuation. Duration is the change in the value of bond that will result from a hundred basis point change in yield. Since this approach uses both

measures - duration and convexity, it is named as duration/convexity approach. Duration is the first approximation of the percentage change in price. Convexity is used to improve the estimate provided by duration.

Duration of the bond is calculated as follows:
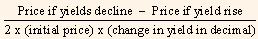
         1063_duration.png

If we assume,

         Δy = Change in yield in decimal.

         V0 = Initial price.

         V- = Price if yields decline by Δy.

         V+ = Price if yields increase by Δy.
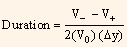
          1990_duration1.png                                                                                  ...Eq.(1)

For example, consider an 8.5% coupon 20-years option-free bond selling at Rs.115.89 to yield 7% (refer table 9). Let's assume that there are both side changes in the yield by 25 basis points. After the increase of 25 basis points from 7.00% to 7.25%, the price decreases to Rs.112.99.  When yield decreases by 25 basis points from 7.00% to 6.75%, the price increases to Rs.118.91.

Substitute values in Eq. (1) to get the duration of the bond as given below:

         Δy = 0.0025

         V0 = Rs.115.89

         V- = Rs.118.91

         V+ = Rs.112.99

Then,

         Duration = 1049_duration2.png
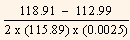
         Duration = 10.22

Duration of 10.22 means that the there will be 10.22% change in the price of this bond for a 100 basis point change in yield.


Related Discussions:- Duration

Return enhancement on investment, Return Enhancement can be explained...

Return Enhancement can be explained using following heads: Use of a Valuation Model: An investor having access to a bond valuation model can bu

How compound values can be calculated on anannual basis, How Compound value...

How Compound values can be calculated on anannual basis Compound values can be calculated on anannual basis, or on a half-yearly basis or on a monthly basis or on continuous ba

Define stress testing and leverage, Lehman Brothers Holdings was a global f...

Lehman Brothers Holdings was a global financial services firm which, until declaring bankruptcy in 2008, participated in business in investment banking, equity and fixedincome sale

Explain common methods for controlling translation exposure, It is, usually...

It is, usually, not possible to totally eliminate both translation exposure and transaction exposure.  In few cases, the elimination of one exposure will as well eliminate the othe

Accounting to budget, Accounting to Budget: Accounting to budget is a c...

Accounting to Budget: Accounting to budget is a commonly used term to describe how an organisation controls its accounting process. Typically, an organisation divides its re

Initial recognition of the financial instruments, a) On 1 st January 2010,...

a) On 1 st January 2010, Grimm issued 400,000 convertible £1 6% debentures  for £600,000.  The professional fees associated with the issue were £40,000 and the fair value of simil

#titleEvaluate alternative hedging strategies, Peak Inc. needs to order Can...

Peak Inc. needs to order Canadian raw materials to use in its production process. The Canadian exporter typically invoices Peak in Canadian dollars. Assume that the current exchang

Swap-linked notes, Swap-Linked Notes: Interest rate swaps are derivativ...

Swap-Linked Notes: Interest rate swaps are derivative products which help in transforming the cash flows of existing debt issues. These are not only useful in covering the exis

Write Your Message!

Captcha
Free Assignment Quote

Assured A++ Grade

Get guaranteed satisfaction & time on delivery in every assignment order you paid with us! We ensure premium quality solution document along with free turntin report!

All rights reserved! Copyrights ©2019-2020 ExpertsMind IT Educational Pvt Ltd